Raising the SS taxable wage cap is popular on social media. It’s another example of trying to shift responsibility and costs to others. Higher income earners are the most likely target. It’s misleading and displays a lack of understanding of Social Security.
This is misleading and illogical.
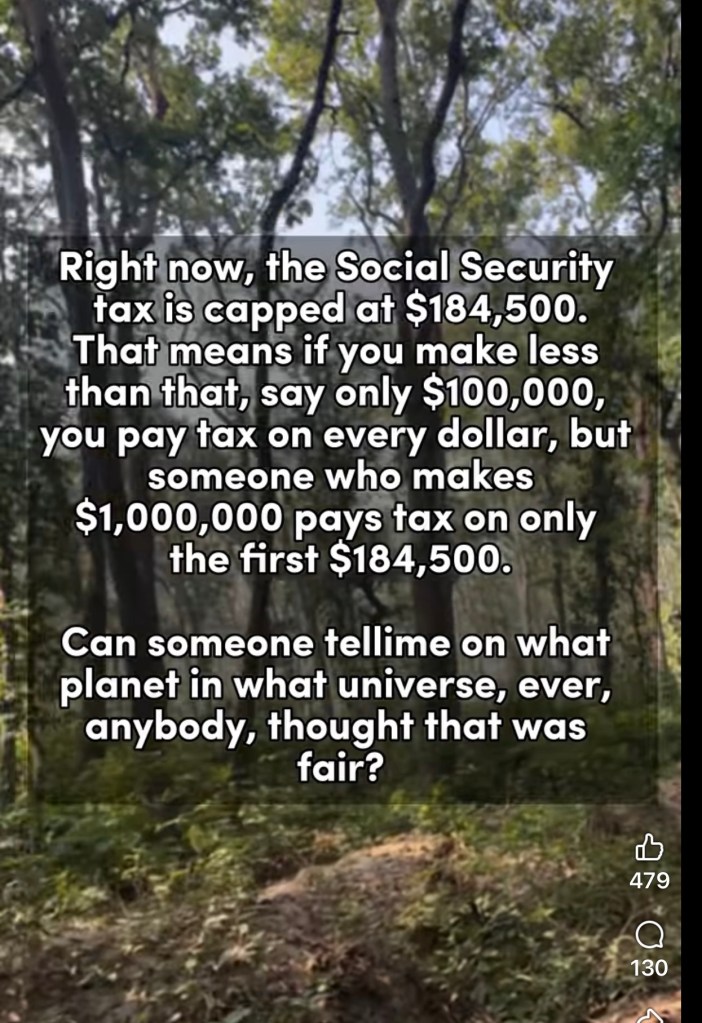
Only 6% of American workers earn above the SS taxable wage cap. That has been true for many years. The very wealthy don’t have earned income or Social Security benefits.
Given that untaxed earnings are not used in the Social Security benefit calculation, those earnings are irrelevant.
The SS taxable wage is adjusted each year with changes in the national average wage index. It will be $192,300 in 2027.
Eliminating the taxable cap would extend the insolvency date of Social Security, 20-25 years, but would not make it sustainable.
For someone retiring at full retirement age (67) in 2026, Social Security replaces a substantially higher percentage of income for someone earning $75,000 than for someone earning $200,000.
Estimated Social Security income replacement
Annual earnings. $75,000. $200,000
Income Replacement rate 51.6%. 24.9%
Estimates assume a 35-year career with consistent, inflation-adjusted earnings and retirement at full retirement age. Figures are illustrative.
Why is there such a big difference?
Social Security uses a progressive benefit formula:
90% of the first $1,286 of average indexed monthly earnings (AIME),
plus 32% of AIME between $1,286 and $7,749,
plus 15% of AIME above $7,749.


Hi Mr. Quinn, real quickly on this topic. While I agree to a point with your thoughts, I also look at the earners who make less than the cap right now. Those earners are potentially losing 12 percent of income to SS. Six percent that they pay directly into. Six percent that their employeers pay into, which could be coming from the pay the employeers could have been paying the employees.
I see the employees below the cap as straight up losing 6 percent of their income to SS. As the income rises, this effective rate goes down and eventually when one gets so high in their pay it is almost zero. Why do the lower earners, who may not be able to afford losing that 6 percent shoulder the entire burden and those who are above the cap shoulder a lesser burden.
Fair is fair. I believe remove the cap, but if we do, we make those who were above the cap able to collect higher amounts of SS. They may not get back all that they paid into it, but there will always be some who paid in who won’t get back their entirety.
LikeLike
And you see that as a practical solution?
LikeLike
It is the only practical, intergenerationally savvy solution – and, as a result, it won’t pass a Congress interested in buying votes.
LikeLike
“Yes, it’s completely fair.”
Nope.
It is what it is, a wealth transfer system, from workers to retirees, from younger Americans to older Americans, from higher paid workers to lower paid workers, from workers who paid into the system for more than 35 years to workers who only paid in for 10 years (40 quarters). It has many “unfair” flaws – it is not equitable, it doesn’t offer:
Horizontal equity: Treating similarly situated people with the same incomes over their working life the same.
Vertical equity – Treating differently situated people differently, proportionately, to their incomes.
For example, I’ve been paying in since 1970, that’s 56 years, but the formula only counts the highest 35. I commenced payout 8 years ago. Why should people continue to contribute when their less than full time wages are low enough such that they do not replace any of the 35 prior years already in the calculation, for benefits in a payout status.
But, importantly, the reason why we have a funding deficit is not because the cap wasn’t raised. Consider, for comparison, how President Clinton eliminated the cap in 1993 – 34 years ago. That change didn’t solve the Medicare Part A funding problem – that trust fund is expected to be exhausted in 2036, just 3 or 4 years later. And, that’s despite Congress adding new taxes to increase funding to Medicare Part A as part of Health Reform.
The last thing we need are more taxes on future wage earners to fill funding deficits because Congress bought votes in the past when they failed to tax workers in the past, some now retired, to pay enough taxes to fund the promises.
The person who posted that note was just one more person who, more likely than not, also failed to pay sufficient FICA taxes to fund the system. We can’t let Congress try (and likely fail) to solve underfunding due to past vote buying by more future vote buying.
LikeLike
I see the system as fair. What is your alternative that would work for all Americans at all income and intellectual abilitiy levels to provide a reasonable foundation for retirement?
LikeLike
My alternative – stop Congressional vote buying … also known as “don’t tax you, don’t tax me, tax that guy behind the tree.”
Social Security is an entitlement.
It is not intended to be nor is it designed to be “fair”.
It is, what it is – a wealth transfer process.
And, after 90+ years, people have become dependent on Congressional vote buying – and they want MORE money transfered to them, and less money transferred from them as they deem to be fair … treating that person as they think they should be treated.
You think each member of Congress’ definition of “fair” is a metric by which America should decide how to fill the gap in SS funding … as opposed to, what, more vote buying?
My alternative is to simply calculate how much each person should have paid in taxes to fund the promises, keeping the existing allocations of burden and benefit, then giving everyone in the system, including retirees, choices on whether to pay more taxes or take a reduction in benefits.
That’s no reason why we should let Congress continue to buy votes and send the bill to generations too young to vote, and generations yet unborn.
LikeLike